
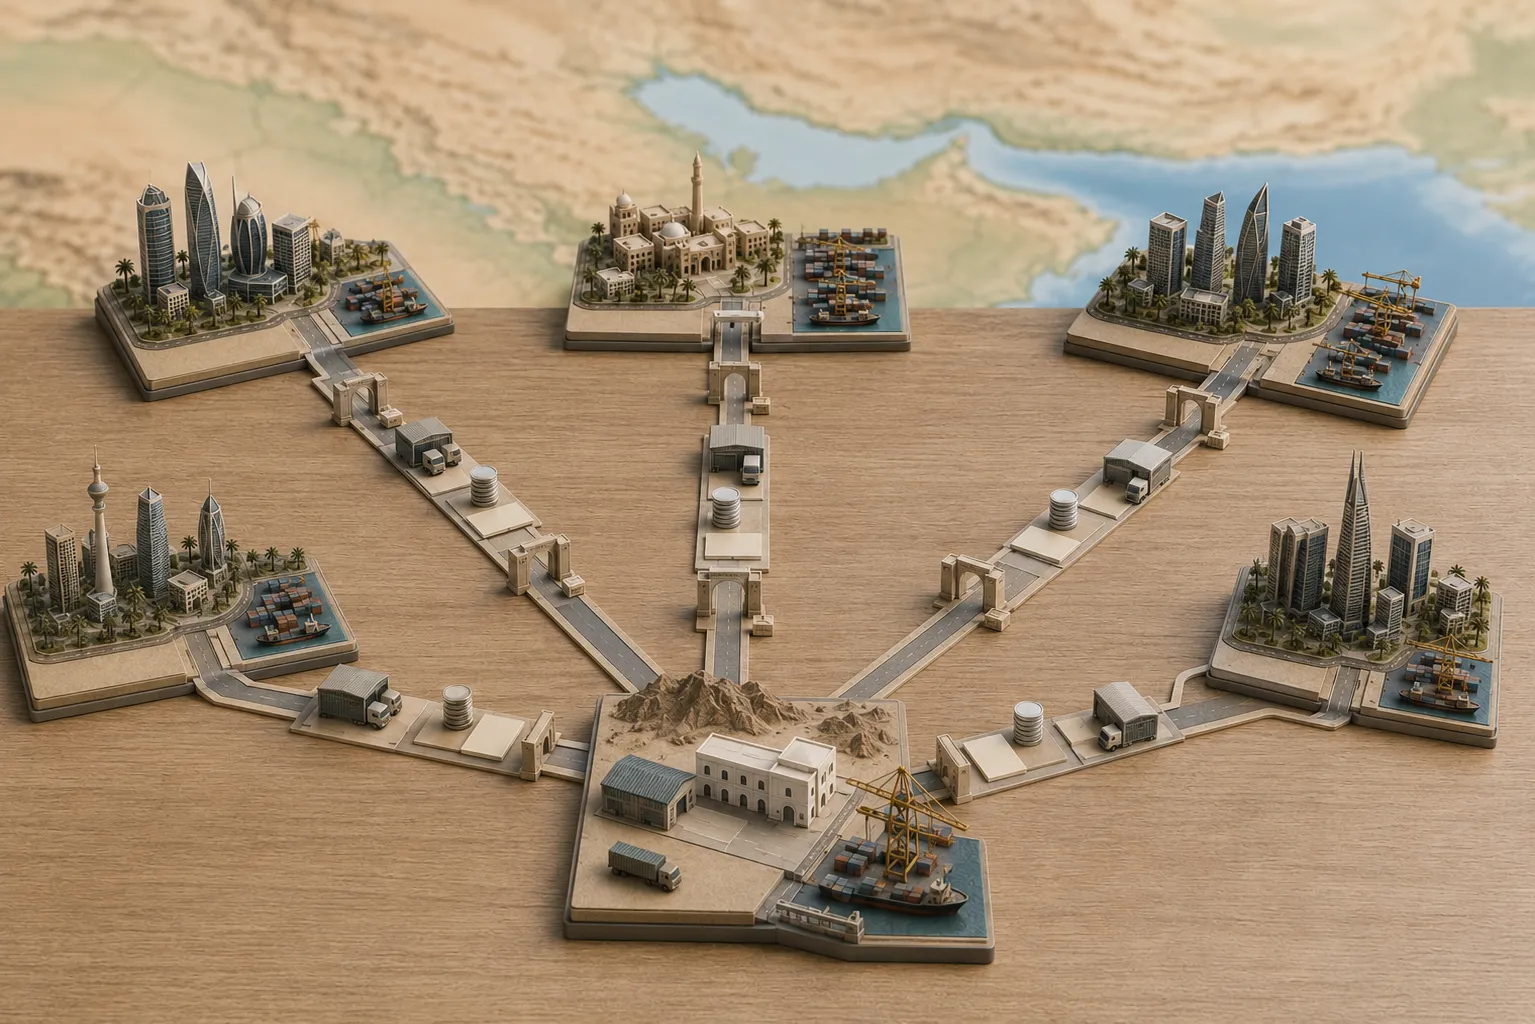
Short answer: yes, an Oman company can sell goods or services to customers in other GCC states. However, an Oman Commercial Registration is not one shared GCC licence. It does not replace the importer, VAT, product-registration or commercial-licensing rules of the destination country.
The right structure depends on what crosses the border. Goods pass through customs. Services usually do not, but they can create tax, professional-licence or local-presence duties. Online sales, warehouses, local staff and government contracts add further checks.
The safest question is not only “Can the Oman company invoice the customer?” It is also “Who imports, who pays VAT, who holds the product approval, and who performs the work in the destination country?”
Quick decision tree
- Are goods entering another GCC state? Name the destination importer, customs procedure, HS code, duty status and product permits.
- Is only a service crossing the border? Check the place of supply, VAT, withholding tax, professional licensing and permanent-establishment risk.
- Will the company keep stock, staff or premises there? Review a local warehouse licence, branch or subsidiary.
- Is the product regulated? Obtain the destination-country registration or approval before shipping.
- Is the customer a government body? Read the tender eligibility, local-content and regional-headquarters conditions before bidding.
At a glance: when is the Oman entity enough?
| Operating model | Can the Oman company contract? | What is still needed? |
|---|---|---|
| Remote B2B service | Often yes | Tax, place-of-supply, sector licence and permanent-establishment review |
| Goods sold to a GCC distributor | Often yes | Destination importer, customs declaration, VAT and product approval |
| Direct online sale to consumers | Sometimes | Importer model, destination VAT, consumer rules, returns and regulated-product checks |
| Stock held in another GCC state | Not by contract alone | Warehouse, customs, VAT and possible local entity or registration |
| Local employees or regular on-site work | Limited cases | Work, professional, tax and branch or subsidiary review |
| Destination-country government contract | Only after tender review | Procurement eligibility, local content, registration and any RHQ rule |
What the GCC Customs Union does
The GCC Customs Union started in 2003. Its framework includes a common customs law, a common external tariff, a first point of entry and national treatment for qualifying goods made in a member state.
Foreign goods are normally inspected and assessed at the first GCC customs entry point. After release, their movement to another member state can use the GCC customs framework. The business must still keep the first-entry declaration, proof of paid duty, invoices, transport documents and any required statistical or transfer records.
The common external tariff is generally 5% for many goods. This is not a universal rate. Exemptions, higher rates, excise tax, anti-dumping measures and product-specific rules can change the result.
What the Customs Union does not do
- It does not create one commercial licence for all six GCC states.
- It does not create one VAT registration for the GCC.
- It does not approve food, medicine, cosmetics, telecom equipment or other regulated products.
- It does not turn Chinese or other foreign goods into Omani goods.
- It does not remove import bans, standards, labelling, health, safety or destination-country controls.
Important: “Duty was paid in Oman” and “the goods may be sold legally in Saudi Arabia, the UAE or another GCC state” are different tests. Customs status, VAT, importer status and product approval must each be confirmed.
Goods and services follow different routes
| Transaction | Main border issue | Main local-market issue |
|---|---|---|
| Physical goods | Customs, origin, value, duty and import VAT | Importer, product approval, distribution and local sale rules |
| Professional service | No goods customs entry | Place of supply, professional licence, withholding tax and permanent establishment |
| Digital service | No physical customs entry | Destination VAT and electronic-service rules |
| Installation with equipment | Goods import plus service element | Contract split, local licence, workers, VAT and tax presence |
| E-commerce order | Parcel import, customs value and importer | VAT, consumer rights, returns and product compliance |
A remote service can be simpler than a goods sale. However, repeated on-site work, a fixed office, staff authority to conclude contracts or a long project can create a taxable or licensed presence. The result depends on domestic law and any applicable tax treaty. Do not use one general day-count rule for every contract.
The importer of record is the key person for goods
The importer of record is the party legally responsible for the import declaration. This party normally provides its customs identity, declares the goods, pays or accounts for customs duty and import VAT, and presents required permits.
A customs broker can submit work for the importer. The broker does not automatically become the owner, buyer, product registrant or importer of record. The sales contract and Incoterms should identify these roles before shipment.
- Distributor-importer model: the destination distributor buys and imports the goods.
- Customer-importer model: the GCC business customer imports under its own registration.
- Seller-delivered model: the Oman seller promises delivery after import. This can create destination customs and tax duties for the seller.
- Marketplace or courier model: the platform or carrier may handle parts of the process, but the contract must confirm who has legal responsibility.
VAT is still country by country
The GCC has a shared VAT agreement, but VAT is administered by each participating state. An Oman VAT number is not a GCC-wide number.
An export of goods from Oman may qualify for the Oman zero rate when the legal conditions and export evidence are met. The destination country can still collect import VAT. The destination importer may recover that VAT only if its own rules allow it.
Saudi Arabia’s official 2026 import and export VAT guide also explains transitional treatment for intra-GCC goods until the GCC electronic-services system is fully applied. A seller should not assume that the customs-union route and the VAT route use the same treatment.
When destination VAT registration may arise
- The Oman seller imports the goods in its own name.
- The seller keeps stock in the destination country.
- The seller makes local supplies after import.
- The seller supplies consumers or electronic services under rules that place the tax in the destination.
- The reverse-charge mechanism does not apply to the transaction.
For cross-border B2B services, the customer may account for VAT under a reverse-charge rule. This is not automatic for every service. Property, events, transport, telecom, electronic services and goods-related work can have special place-of-supply rules.
Product registration remains local
A product accepted in Oman is not automatically accepted in every GCC state. The destination authority can require its own importer registration, product file, label, test, certificate or prior approval.
| Product group | Possible destination check |
|---|---|
| Food and beverages | Foreign establishment, local importer, product, label, health and border-clearance requirements |
| Medicines and medical devices | Marketing authorisation, authorised representative, establishment licence and technical file |
| Cosmetics | Product notification or registration, ingredients and Arabic label rules |
| Electrical goods and toys | Conformity, safety testing, energy or quality marks |
| Telecom equipment | Type approval or communications-authority release |
| Chemicals and controlled goods | Safety data, environmental, security or sector permits |
Saudi Arabia is a clear example. The Saudi Food and Drug Authority states that foreign food establishments, Saudi food importers and customs brokers use its import-control systems. Medical devices follow a separate SFDA route. An Omani approval alone does not replace those steps.
Rules of origin and Oman manufacturing
GCC-origin goods can receive national-product treatment when they meet the applicable origin requirements. This can help a real manufacturer in Oman. It does not help a business that only stores, invoices, relabels or resells foreign goods.
Origin can depend on the production process, imported materials, value added, tariff-classification change, factory records and the exact agreement or GCC rule. Oman Customs warns that a certificate of origin alone may not settle the origin question. Customs can review the real production evidence.
Origin test: company address ≠ shipping port ≠ invoice country ≠ legal origin. Ask Oman Customs for an advance ruling when classification or origin is important to the business model.
Distributor, commercial agent or direct sale?
A local distributor can be enough when it buys, imports and resells the goods. The Oman company remains the exporter or supplier. This model can avoid the need for the Oman company to hold local stock or make local retail sales.
A commercial agency is a more formal legal relationship. Registration, ownership, territory, exclusivity, after-sales service, spare parts and termination rules can apply. In Saudi Arabia, the official implementing regulations state that a Saudi company acting as a commercial agent must have 100% Saudi capital, with Saudi board members and authorised signatories.
Do not call every reseller an “agent.” The contract should state whether the local party is a buyer-distributor, commission agent, registered commercial agent, franchisee, logistics provider or authorised product representative.
Businesses that need introductions to distributors, suppliers or customers can review B2B market-entry coordination in Oman. Any introduction still needs legal, commercial and compliance due diligence.
When a branch or local subsidiary becomes practical
A distributor is not always enough. A local entity may be needed or commercially useful when the business wants to invoice locally, hire staff, lease a warehouse, import in its own name, provide regulated work or hold long-term contracts.
| Sign of local presence | Why it matters |
|---|---|
| Permanent stock or warehouse | Customs, VAT, premises and local operating licences may arise. |
| Employees in the market | Work permission, payroll, tax and local entity rules may apply. |
| Regular installation or maintenance | The activity may need a professional or contractor licence. |
| Local consumer invoices | VAT, consumer, e-commerce and return obligations increase. |
| Long project or fixed office | A permanent establishment or branch duty may arise. |
| Government or regulated customer | Tender and supplier-registration conditions may require local substance. |
A branch is not automatically lighter than a subsidiary. Each destination country sets its own foreign-investment, activity, capital, manager, office and filing rules.
E-commerce and direct online sales
An Oman website can accept an order from another GCC state. This does not remove border and destination rules. The seller must decide who imports the parcel, who pays duty and VAT, and who handles product compliance and returns.
- Show the seller’s legal name and clear contact details.
- State whether the price includes destination duty, VAT and delivery charges.
- Confirm whether the customer or seller is the importer.
- Check product labels and restrictions before accepting orders.
- Set a real returns and rejected-shipment process.
- Review destination VAT registration before repeated consumer sales.
A courier’s “delivered duty paid” service is useful only when the legal importer, tax and product roles are clear. A shipping label does not replace a licence or product approval.
Saudi customer and government-contract scenarios
Private Saudi customer
An Oman company can often sign a private B2B contract with a Saudi customer. For goods, the contract should name the importer and product registrant. For services, the parties should review Saudi VAT, withholding tax, the place of performance, professional licensing and permanent-establishment risk.
If the Oman team will work repeatedly in Saudi Arabia, supervise staff, install equipment or negotiate contracts there, a remote invoice may not be enough. Obtain Saudi legal and tax advice for the exact contract.
Saudi government or state-linked contract
Saudi government procurement can apply special controls to contracting with companies that do not have a regional headquarters in the Kingdom. Tender scope, bidder identity, group structure, value, exceptions, local content and supplier registration all matter.
Do not assume that every private Saudi sale needs an RHQ. Also do not assume that an Oman entity can bid remotely for every government contract. Review the live tender and current Saudi rules before spending money on a bid or local structure.
How SOHAR, Salalah and Duqm can change the logistics model
| Location | Possible fit | What it does not solve |
|---|---|---|
| SOHAR | Port-linked import, industry, storage and distribution serving northern Oman and regional routes | Destination importer, VAT, origin and product approval |
| Salalah | Arabian Sea transshipment, export processing and routes toward East Africa and South Asia | Automatic GCC-origin status or mainland market access |
| Duqm | Large industrial, energy, processing, port and long-term logistics projects | A general solution for small-volume GCC retail distribution |
A free zone can delay customs duty while goods remain under an approved suspension or zone procedure. Duty and import VAT can arise when goods enter a GCC mainland market. Manufacturing in a zone also does not guarantee GCC origin.
Choose the location from the cargo, factory, customer and port route. Investors comparing export-oriented structures can use Oman free-zone selection advisory.
Five worked market-access scenarios
1. Chinese finished goods enter Oman, then move to Saudi Arabia
The goods remain Chinese-origin unless qualifying production changes their origin. If they are released at an Omani first point of entry, keep the Oman declaration and proof of duty status. Before onward movement, name the Saudi importer and confirm the Saudi customs record, import VAT, product approval and any restricted-goods requirements.
2. Chinese stock stays in an Oman free zone and is shipped to the UAE
The zone can support storage and re-export without first releasing the stock into mainland Oman. When the goods enter the UAE mainland, the UAE importer and customs process take over. The Oman free-zone address does not create Omani origin or remove UAE VAT and product rules.
3. A factory makes goods in Oman for GCC customers
The goods may qualify for GCC national-product treatment if the origin rule is met and proved. The factory should keep its industrial licence, bill of materials, production records, cost data and accepted origin evidence. The destination can still require product registration, labels, import records and VAT treatment.
4. An Oman consultancy serves a Saudi customer
No physical goods enter customs. The contract can still create Saudi VAT, withholding tax, professional-licence or permanent-establishment questions. Remote work from Muscat is different from sending a team to work for months at the customer’s site.
5. An Oman online shop sells to GCC consumers
The seller should map every destination separately. Identify the parcel importer, duty and VAT payer, product approval, consumer disclosures, returns and rejected-delivery process. Repeated sales or local stock can create destination registration duties.
Oman company and customs pathway
- List the goods, services, destination countries and customer types.
- Confirm that the Oman entity has the correct commercial activities. You can search Oman commercial activity codes. The tool does not prove foreign-ownership eligibility, licence approval or regulator acceptance.
- Choose mainland or free zone from the real cargo and customer flow.
- Complete the Oman entity and activity route. Use Oman company setup advisory when the legal structure needs review.
- Register the company and authorised users in Oman Customs’ Bayan system where needed.
- Confirm the HS code, origin, value, permit and customs procedure for each product.
- Name the destination importer, product registrant and VAT party before signing the delivery promise.
- Prepare the invoice, packing list, transport record, origin proof and permits. Businesses needing shipment support can review customs documentation support in Oman.
Common mistakes
- Calling an Oman licence a “GCC licence.”
- Confusing customs-union access with VAT registration.
- Shipping before the destination importer is confirmed.
- Using the supplier’s HS code without checking the destination tariff.
- Assuming first-entry duty removes all later border documents.
- Treating a free-zone address as proof of Omani origin.
- Using a courier without defining the importer and tax payer.
- Calling a distributor a registered commercial agent without checking the legal effect.
- Ignoring withholding tax and permanent-establishment risk on service contracts.
- Bidding for a government contract before checking local and RHQ conditions.
Practical checklist
- Exact goods, services and HS codes listed.
- Oman activities and licences confirmed.
- Mainland, free-zone or bonded route selected.
- Origin tested from production evidence.
- Destination importer named in writing.
- Incoterms and delivery responsibility agreed.
- Customs duty and import VAT checked.
- Destination VAT registration reviewed.
- Product approvals and labels complete.
- Distributor or agency contract reviewed.
- Staff, warehouse and local-presence plan checked.
- Withholding tax and permanent-establishment review completed for services.
- Government tender eligibility checked where relevant.
- Full evidence file ready before shipment or contract start.
Frequently asked questions
Does an Oman company have the right to trade in all GCC countries?
It can make cross-border sales, but its Oman licence does not replace destination-country import, tax, product or commercial rules.
Is customs duty paid only once in the GCC?
The Customs Union uses a first-point-of-entry principle for foreign goods. Correct proof of duty status and movement records are still needed. Exceptions, special procedures and destination controls can apply.
Do goods shipped through Oman become Omani goods?
No. Transit, storage, invoicing, relabelling or simple resale does not normally create Omani origin. The goods must meet and prove the applicable origin rule.
Can the Saudi customer act as the importer?
Yes, when the customer has the required importer and product position and the contract gives it that responsibility. Confirm this before shipment.
Does the Oman company need VAT registration in every GCC state?
Not always. Registration depends on the transaction, importer, stock location, customer type, place of supply and each country’s rules. One Oman VAT number is not valid as a GCC-wide registration.
Can a free-zone company distribute across the GCC without duty?
No general promise is safe. A zone can suspend duty while goods remain under the approved procedure. Duty, VAT and permits can apply when the goods enter a mainland market.
Is a distributor enough for every product?
No. Regulated goods may need a locally eligible importer, authorised representative, product registrant or licensed facility in addition to a distributor.
Can an Oman company bid for Saudi government work?
Only after the live tender and Saudi procurement rules are reviewed. Bidder identity, local registration, local content, group structure and regional-headquarters controls can affect eligibility.
Related Oman Verified guides
Oman’s trade agreements
Review active agreements, origin tests and customs evidence for qualifying goods.
Oman Customs and Bayan registration
Understand company registration, users, customs access and shipment limits.
Import, export and wholesale activities under one Oman company
See how activities, products, Customs and sales channels fit under one CR.
Logistics and freight-forwarding requirements in Oman
Separate freight forwarding, warehousing, transport and customs-broker roles.
Conclusion
An Oman company can be the regional seller, service provider, manufacturer or logistics base. It cannot use one Oman licence as automatic permission for every GCC market.
For each route, separate five questions: customs, importer, VAT, product approval and local commercial presence. When all five are clear, Oman can support a practical GCC operating model.
International founder support
Oman Verified works with international founders and investors comparing Oman with other GCC markets and can coordinate the Oman-side setup and implementation when Oman is the selected route. Company registration, customs treatment, origin status, tax treatment, product approvals, banking, immigration and market access are completed through the relevant authorities and institutions in each destination market, with specialist legal, tax and sector work coordinated where required.
Official sources
- GCC General Secretariat — Process of the Customs Union
- GCC General Secretariat — The Customs Union of the GCC Member States
- Oman Customs — Advance rulings on classification and origin
- Oman Customs — Create a customs declaration
- Oman Tax Authority — VAT guide for imports and exports
- Oman Tax Authority — VAT guide for electronic commerce
- Oman Tax Authority — VAT guide for special zones
- Saudi ZATCA — Imports and exports under VAT provisions, 2026
- Saudi ZATCA — Register as an importer or exporter
- Saudi Ministry of Commerce — Commercial Agencies Law
- Saudi Ministry of Commerce — Implementing Regulations of the Commercial Agencies Law
- Saudi Food and Drug Authority — Imported-food controls
- Saudi Ministry of Investment — Investor Guide 2026
- OPAZ — SOHAR Free Zone
- OPAZ — Salalah Free Zone
- OPAZ — Special Economic Zone at Duqm
Official public information reviewed on August 10, 2026. Confirm the current requirements in the live government systems before submission.
